

What's Driving Portfolios Beneath the Surface?
Terry Herr, CFP®
Investors often use major indices like the S&P 500, Nasdaq Composite, and Dow Jones Industrial Average as a way to understand how financial markets are performing. While this is a helpful place to start, the reality is that the stock market is made up of many thousands of companies, each affected by economic and market trends in unique ways. To understand these trends, stocks are often grouped into sectors, geography, and by other characteristics such as the size of the company or the style of investment. Each of these groups can play an important role in long-term portfolios.
While headlines about the S&P 500 reaching new highs or the Nasdaq being driven by artificial intelligence can make it seem as though all stocks are moving together, there is often much more happening beneath the surface. This is especially relevant today because many of the drivers, including AI, oil prices, interest rates, and tariffs, affect all parts of the market, not just large cap stocks. Understanding these drivers can help investors stay balanced and position their portfolios for long-term goals.
Areas of the market including small caps, value stocks, and international companies have outperformed over the past year, and their valuations have generally been more attractive. Understanding how sizes and styles have performed can help investors maintain balance. What is happening beneath the surface of the broad market indices, and what does it mean for investors?
Different sizes and styles are affected by market conditions in unique ways
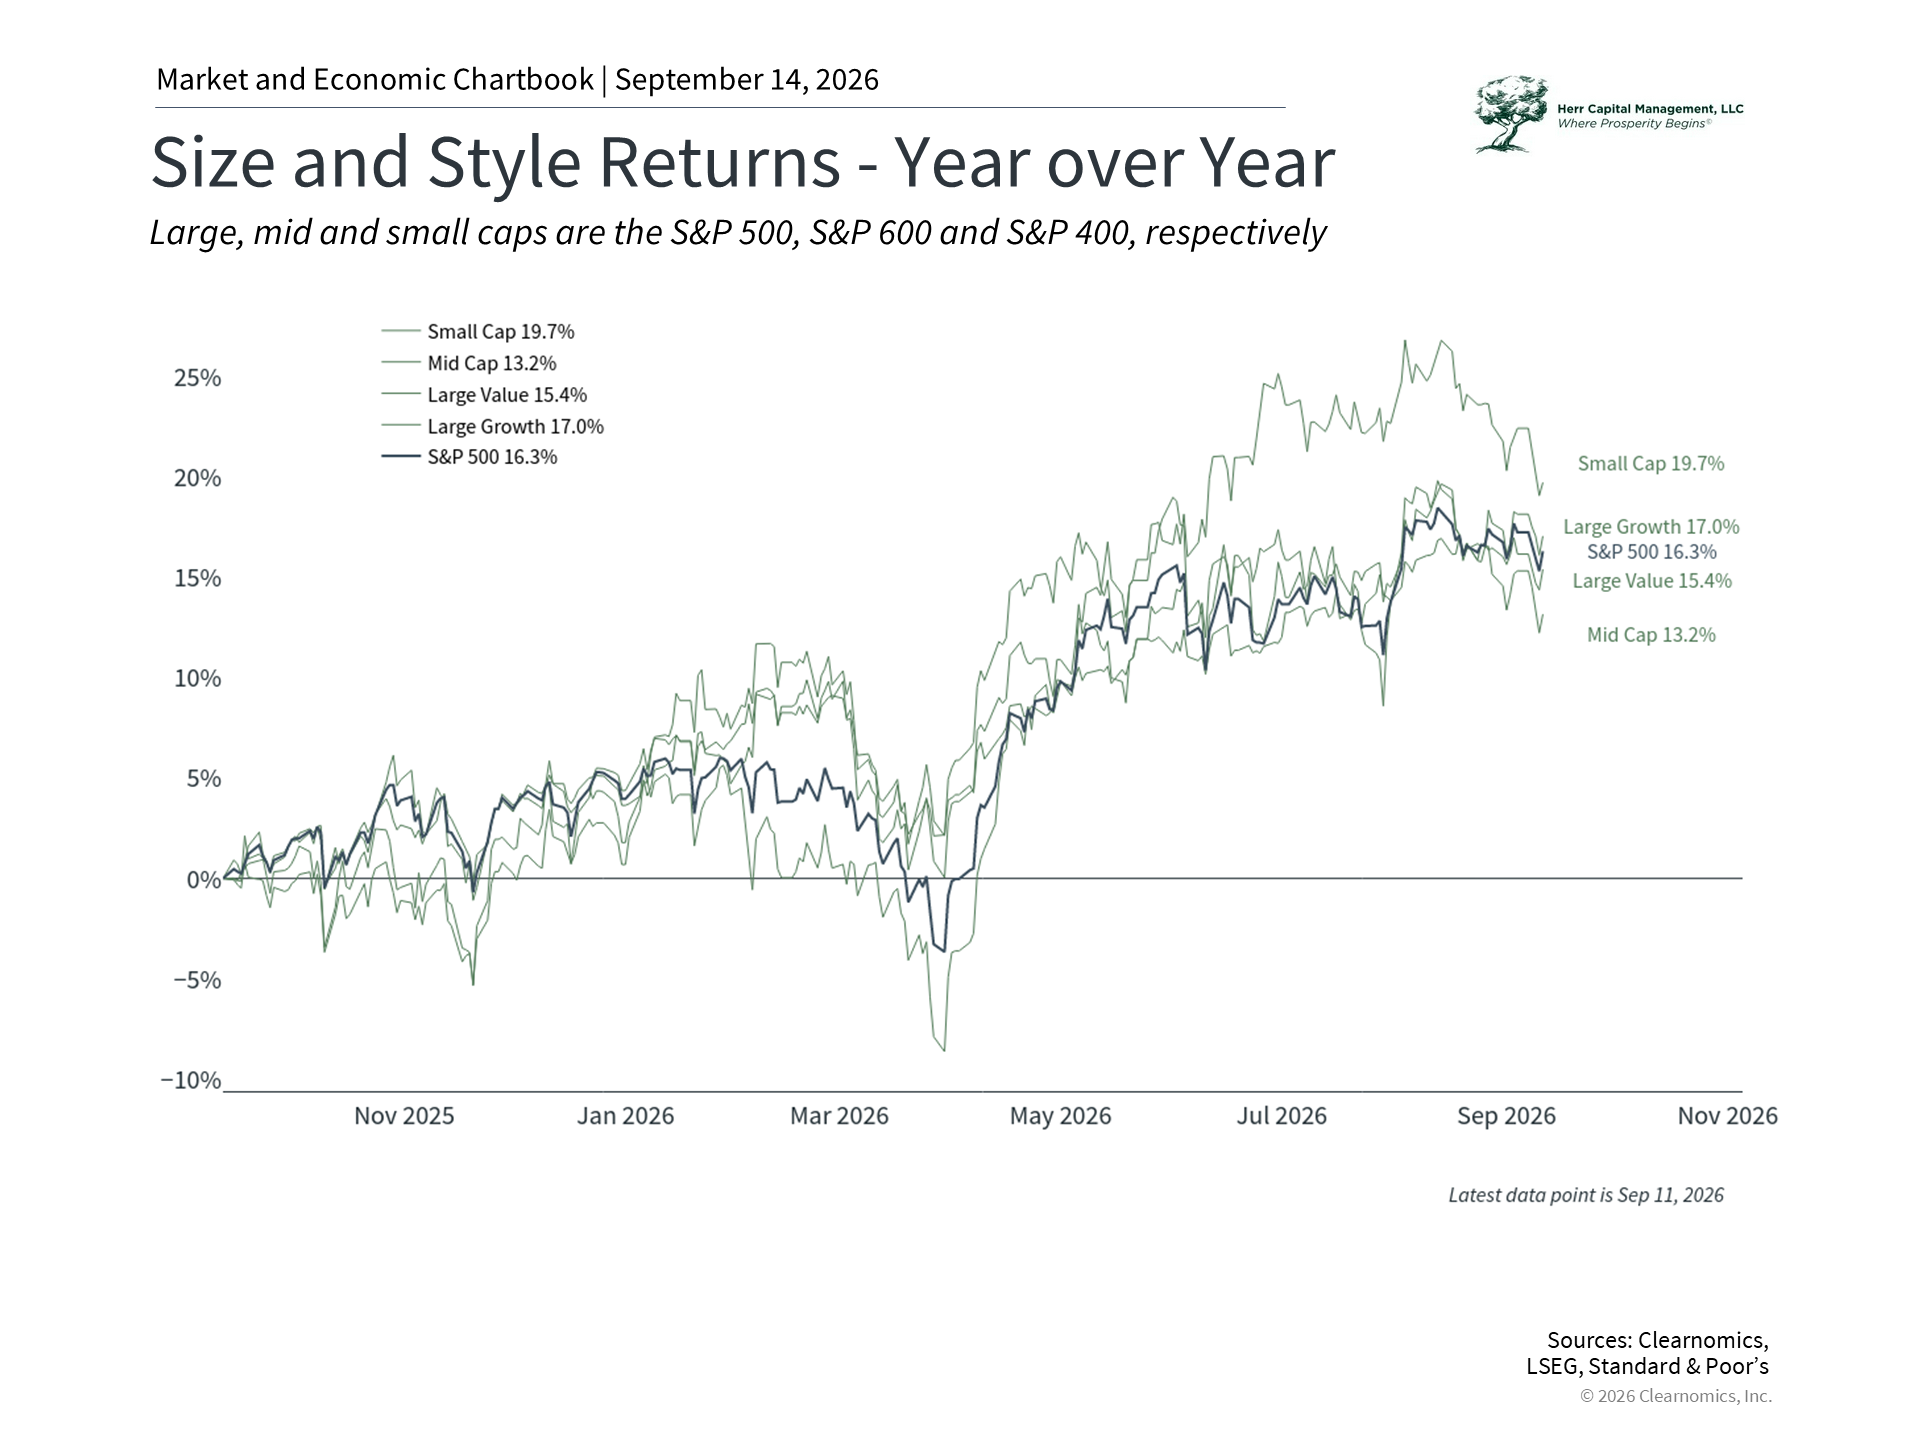 |
While the overall market has experienced double-digit returns this year, at least two important trends have been taking place beneath the surface.1 First, value stocks have outperformed over the past year, a reversal of the trend since 2022 when growth stocks generated strong returns due to technology and AI investments.2
The distinction between value and growth is an important one for investors, and has been the source of much academic research over the past 50 years.3 Value is often defined as companies with attractive valuation ratios, since their prices are low relative to fundamentals such as earnings or sales. Growth, on the other hand, refers to those stocks with higher valuations that reflect expected increases in earnings and market share, and often represents trends that investors are enthusiastic about. The specific companies these represent can change over time, such as dot-com stocks in the late 1990s and AI stocks today.
Value stocks have outperformed this year for many reasons, including uncertainty around interest rates and the outperformance of the Energy sector due to high oil prices.4 Interest rates are near multi-decade highs, which tends to affect growth stocks more. This is because their prices are based on future growth, and higher interest rates reduce the value of future cash flows.
Second, small cap stocks have outperformed large cap stocks this year, reversing a general trend that had lasted well over a decade. In fact, prior to this year, small cap stocks had underperformed the S&P 500 since 2020.5
Small caps have been strong this year for many of the same reasons as the rest of the market. AI, for instance, is often viewed as a large cap opportunity, but many smaller industrial and technology companies supply the equipment, components, and services needed to build data centers and other infrastructure. As a result, these businesses are experiencing healthy revenue and earnings growth today that rivals many other parts of the market.
One challenge is that small caps are often more sensitive to interest rates since they have less access to financing than large cap companies. This has created uncertainty across this group more recently as long-term rates remain high and the possibility of Fed rate hikes increases. However, history shows that this is not always the case. Two of the strongest periods for small cap relative performance occurred in the late 1970s and the mid 2000s, both of which featured higher interest rates and inflation.6 There are many reasons for this, such as the fact that smaller businesses can sometimes raise prices more easily, boosting their operating margins.
Valuations matter for long-term investing
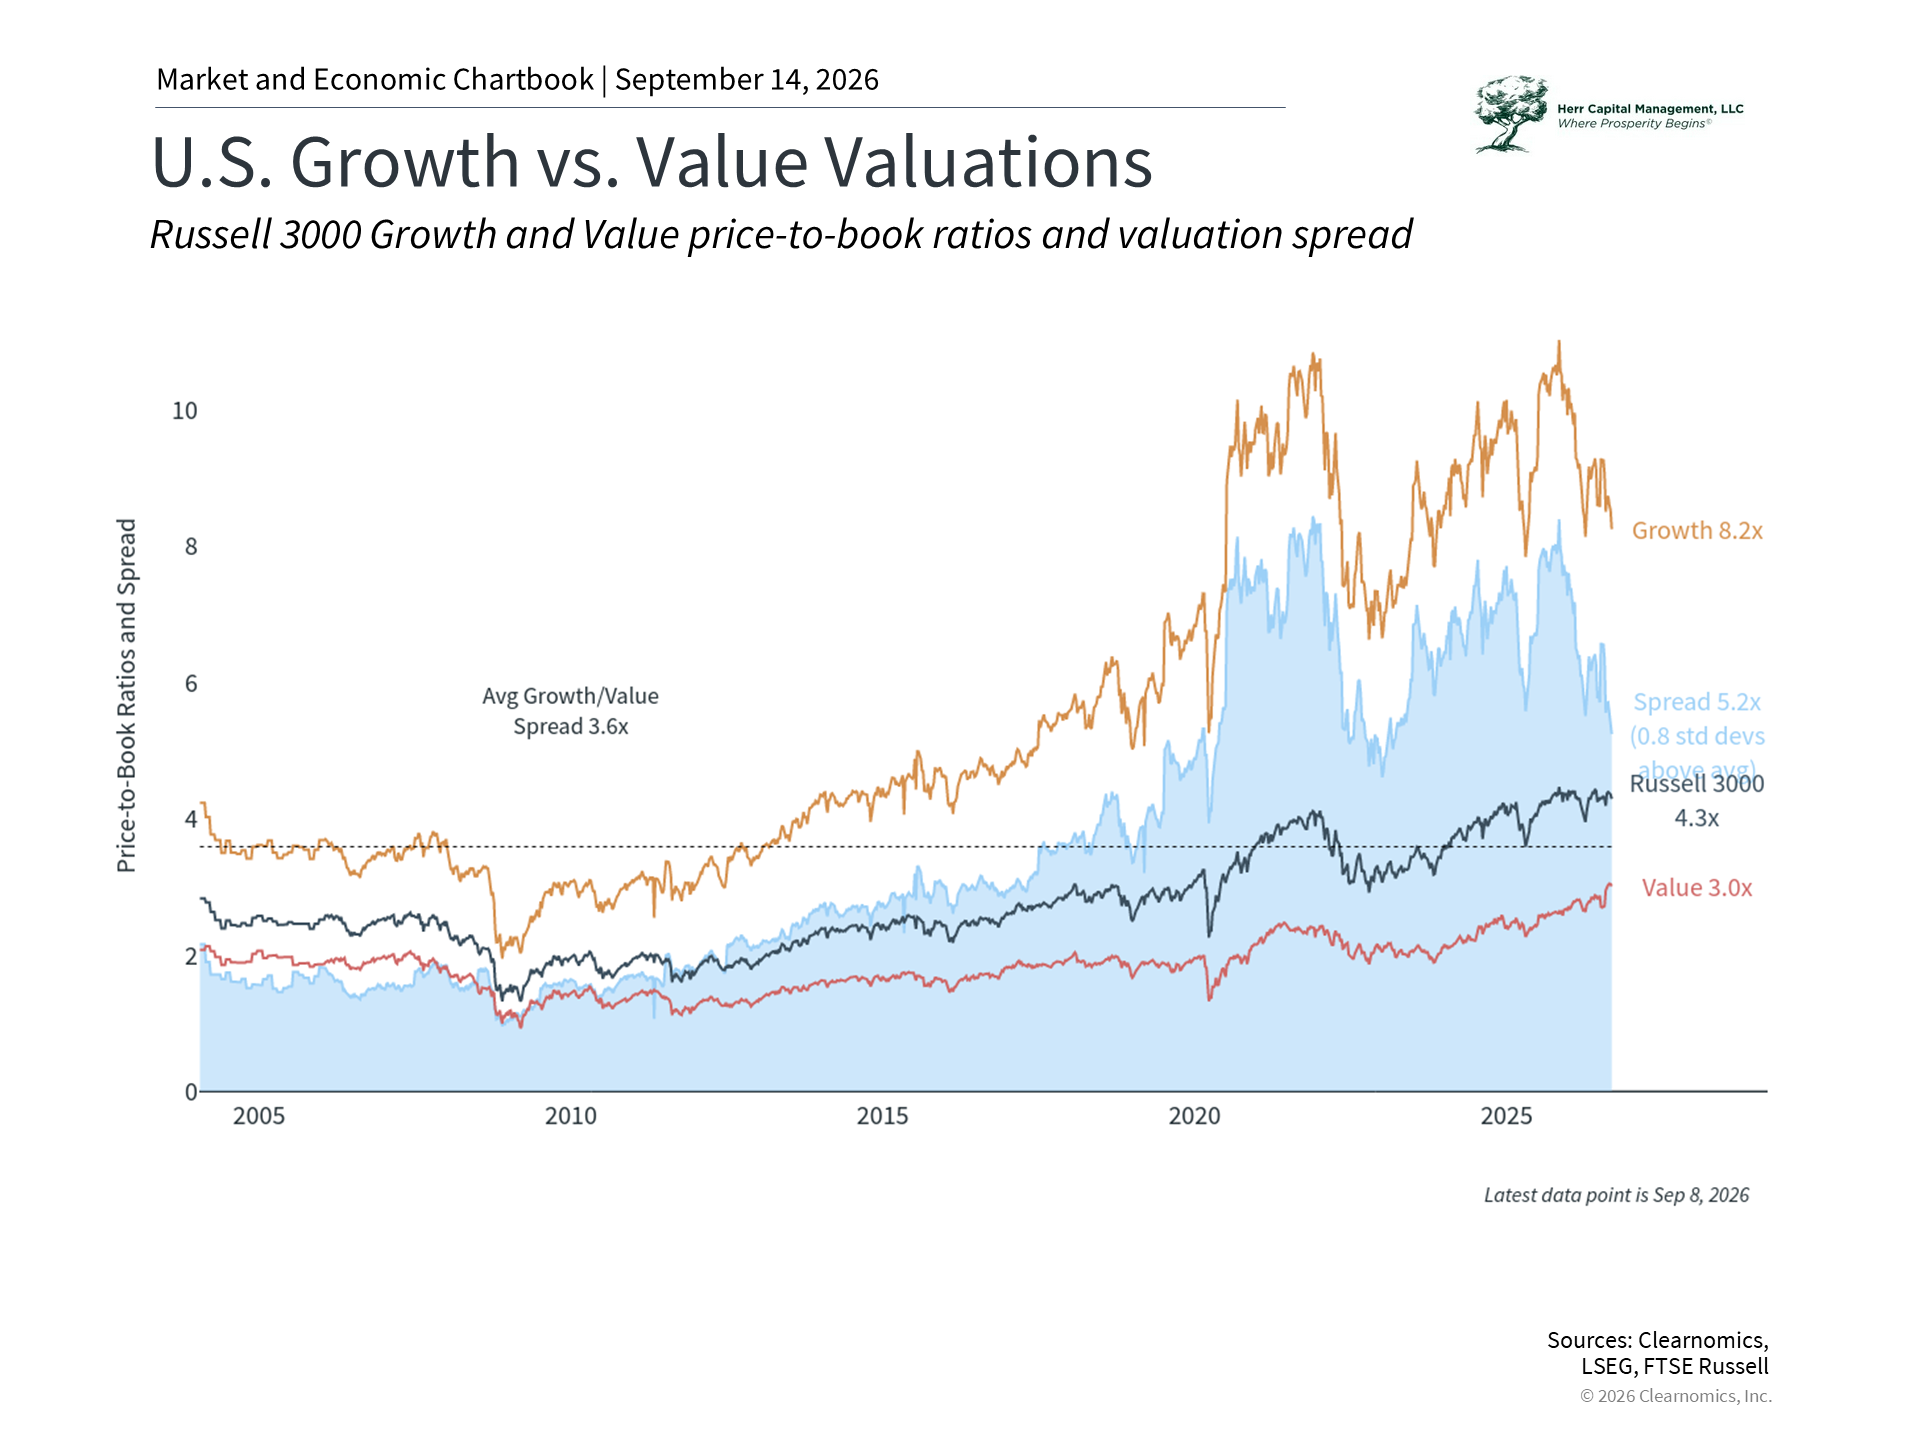 |
The importance of different stock market styles is not just about past returns, but about valuations as well. In the long run, lower valuations have historically supported forward returns, so it’s important to consider all parts of the market.
The stock market is often said to experience “regimes,” or periods when certain investment styles outperform. These regimes can last months, years, or even decades. Perhaps the most studied is the fact that value stocks led for much of the 20th century until growth took over during the dot-com era.
The accompanying chart shows the difference between growth and value valuations using the price-to-book ratio. Growth stocks, particularly the largest technology companies, are hovering near historically high valuations.7 By comparison, value stocks and smaller companies are more attractively priced. As always, past performance does not guarantee future results, so these valuation differences do not ensure that value or small caps will continue to outperform. However, it does help explain why market leadership has shifted, and why investors should consider different parts of the market in their portfolios.
The important lesson is not to try to time these shifts, but to recognize that no single trend lasts forever. This is why holding an appropriate balance across styles and sizes, rather than chasing what has recently worked, has served investors well over history.
International markets are another source of diversification
 |
The same reasoning that applies within the U.S. market also applies across geographies. Just as different sizes and styles respond differently to economic trends, so too do markets around the world. This is why international diversification can be an important tool for long-term investors.
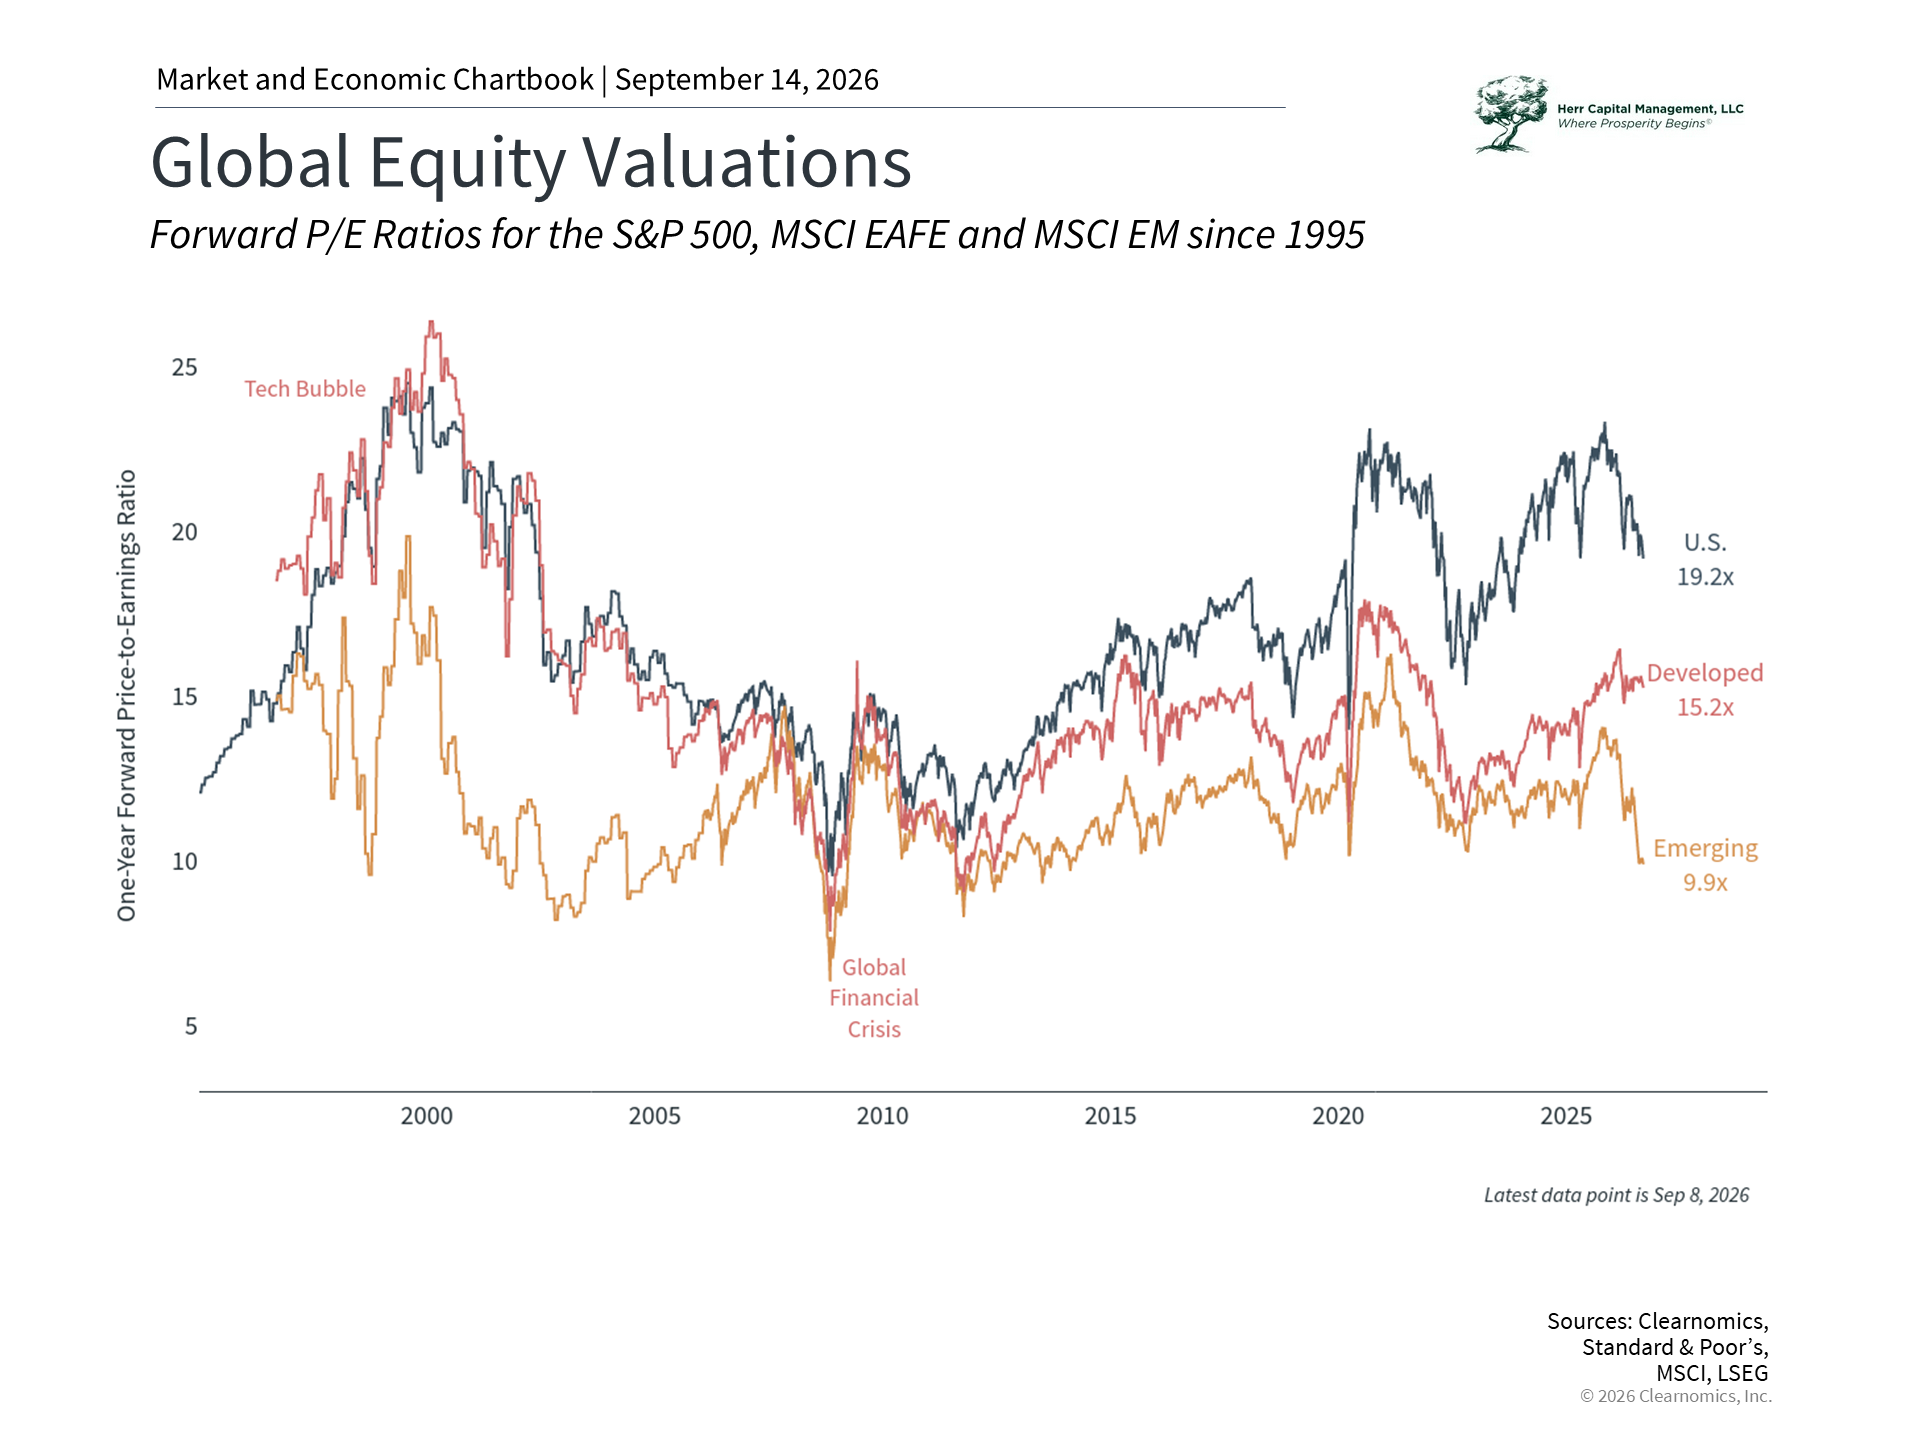
Emerging market stocks, for instance, have performed well this year as earnings growth expectations have improved and valuations have become more attractive.8 The accompanying chart shows that valuations for emerging market and developed market stocks remain well below those of the U.S. across many measures. While U.S. stocks outperformed for much of the past decade, returns since the beginning of last year show that this can change unexpectedly.
Of course, international investing carries its own set of risks, including geopolitical, currency, and regulatory considerations. These risks are precisely why international stocks behave differently than U.S. stocks over time. That said, many U.S. multinational companies also have high international revenues, which naturally offer geographic diversification. When combined thoughtfully with domestic holdings, they can improve the balance of a portfolio.
Ultimately, which parts of the market fit into a portfolio depends on each investor’s specific needs, goals, and risk tolerance. The point is not to predict whether small caps will continue to lead or whether value stocks will keep outperforming. Instead, it’s important to recognize that the stock market is far broader than the handful of companies that dominate the headlines.
The bottom line? While it’s helpful to start with major indices when investing, not all parts of the market behave the same way. Staying balanced across sizes, styles, and geographies is an important way for investors to build a portfolio aligned with long-term financial goals.
References:
- S&P 500 Index as of September 11, 2026
- Clearnomics research and the Russell 3000 Value and Growth indexes, as of September 11, 2026
- Fama and French, 1992, “The Cross-Section of Expected Stock Returns,” https://www.jstor.org/stable/2329112
- Clearnomics research, LSEG and FTSE Russell, as of September 11, 2026
- Clearnomics research and the Russell 2000 Index, as of September 11, 2026
- Banz, 1981, “The Relationship Between Return and Market Value of Common Stock,” https://www.sciencedirect.com/science/article/abs/pii/0304405X81900180
- Clearnomics research, LSEG and FTSE Russell, as of September 11, 2026
- Clearnomics research and the MSCI Emerging Markets Index, as of September 11, 2026
Index Descriptions: S&P 500 The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries. Russell 3000 The Russell 3000 Index is a stock market index that tracks the performance of the 3,000 largest companies listed on the U.S. stock exchange. Russell 2000 The Russell 2000 Index is a capitalization-weighted index designed to measure the performance of the small-cap segment of the U.S. equity universe. It includes approximately 2,000 of the smallest securities in the Russell 3000 Index. MSCI Emerging Markets Index The MSCI EM (Emerging Markets) Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of the emerging market countries of the Americas, Europe, the Middle East, Africa and Asia. The MSCI EM Index consists of the following emerging market country indices: Brazil, Chile, Colombia, Mexico, Peru, Czech Republic, Egypt, Greece, Hungary, Poland, Qatar, Russia, South Africa, Turkey, United Arab Emirates, China, India, Indonesia, Korea, Malaysia, Philippines, Taiwan, and Thailand. MSCI EAFE Index The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the US & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK.
Herr Capital Management, LLC is a registered investment advisor domiciled in Illinois.
This content is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider. Products or services mentioned on this Site will not be made available to persons resident in any state or territory where such distribution would be contrary to local law or regulation.
Copyright (c) 2026 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company's stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security--including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.